Ramp vs. Stripe: Which is best for your business?
Both Ramp and Stripe are trusted fintech platforms used by businesses worldwide. Even though both deal with money management, they solve different challenges. Ramp focuses on corporate spend and expense management, while Stripe focuses on payment processing and online transactions.
This guide will help you understand which platform fits your business needs, works better with your existing stack, or whether your company may actually need both.
REVIEWED BY
Akanksh Muniyappa
Head of Product
WRITTEN BY
K T Haritha
Content Writer
Quick summary: Ramp vs Stripe
| Key factors | Ramp | Stripe |
|---|---|---|
Corporate cards & spending controls | Partial | |
Embedded payments | ||
Payment processing & infrastructure | ||
Expense management & spend controls | ||
Migration & switching considerations | Partial | |
Pricing & plans | Partial | |
Accounting & ERP integrations | Partial | |
Company budget & size | ||
Customer support & onboarding | Partial | |
Security & compliance |
Ramp
Ramp is an American multinational financial technology company. It is an inbound spend management tool.
Primarily position: An AI-powered financial operations platform that provides corporate cards, expense management, bill pay, travel, treasury, and procurement.
Evolution: Founded in March 2019, to replace manual receipt collection and expense logging. Today, it has evolved into an AI-powered spend management platform that handles approvals, flags fraud, reviews policy violations, and syncs data.
Best for: Startups, SMBs and mid-market businesses and Companies incorporated as LLCs
| Pros | Cons |
|---|---|
Free core platform with corporate cards, expense management, and accounting integrations. | Does not support customer payment processing or subscription billing. |
Strong automation features for receipt matching, spend tracking, and approvals. | Some advanced features require paid plans. |
Instant virtual cards with spending limits and merchant controls. | Primarily designed for US-based businesses and finance workflows. |
Stripe
Stripe, Inc. is an Irish-American multinational financial services and SaaS company. It is a global payment processing platform.
Primary position: A versatile financial infrastructure platform that helps businesses control the movement of money in the digital world.
Evolution: Founded in September 2011, focused on simplifying online payment acceptance. Now, it has evolved into an economy infrastructure platform that supports splitting funds across platforms, issuing cards, managing subscriptions, and handling taxes.
Best for: Developers and tech companies, marketplaces, global businesses, SaaS companies and startups.
| Pros | Cons |
|---|---|
Strong payment infrastructure with support for global payments, multiple currencies, and local payment methods. | No built-in expense management or corporate spend controls. |
Provides developer tools, APIs, and documentation for payment integrations. | Transaction fees can become expensive as payment volume grows. |
Broad product ecosystem covering subscriptions, fraud prevention, billing, tax, and embedded payments. | Customer support for smaller businesses is often more self-service than hands-on. |
In-depth comparison: Ramp vs. Stripe
Here, you will find a Stripe vs. Ramp comparison across the 10 key decision factors that matter for businesses to manage payments, expenses, and financial operations.
Which tool is right for you?
Ramp
Ramp is best suited for startups, SMBs, mid-market businesses, and LLCs.
Stripe
Stripe is best suited for developers, tech companies, marketplaces, SaaS businesses, startups, and global organizations.
Get your team working with Volopay
Key factors to consider in choosing the right product for you
Corporate cards & spending controls
Choosing a company with a corporate card program lets you decide who gets to carry the card and identify your team's financial behaviour. It allows you to control uncontrollable spending. A good corporate card program helps you check whether the policy is applied structurally at the point of purchase. With this feature, you can look into the reason why that purchase was made and set specific spending limits. You can categorize by merchant, category, amount, location, or time of the day.
Embedded payments
Embedded payment is a one-stop transaction solution where end users can complete payments without moving across multiple pages or websites. Here, the platform becomes a participant in your payment environment, introducing KYC obligations, fraud monitoring responsibilities, and money transmission licensing requirements. It provides transaction options such as ACH, card networks, or other real-time payment rails. This factor improves speed and convenience for end users while also helping businesses understand employee spending patterns.
Payment processing and infrastructure
Completing transactions within one or two days is important for every user. To make the process easier, businesses need a payment processing system that does not create too many issues during authorization. A good system helps manage the flow of money through a simple dashboard, clear processes, reasonable percentage fees, and easy rules to follow.
Infrastructure works in the background and supports both local and global payment methods that help you to scale your business. It also depends on the market you are targeting. For example, accepting SEPA transfers in Europe, UPI in India, or PIX in Brazil can affect whether you gain, keep, or lose consumers.
Expense management & spend controls
Still relying on spreadsheets without an expense tool is risky for your business. So, what are the criteria for choosing the right expense tool? A good expense management system should capture purchases the moment they are made, provide real-time coding, and support simple approval routing. It helps flag transactions that do not comply with company policy before they are processed. Employees can receive reimbursements within 24 hours of submission instead of waiting for months. A multi-level approval workflow also helps keep spending within budget.
Migration & switching consideration
While choosing the right tool, businesses also need to consider how difficult it will be to switch platforms later. Many companies continue using software that no longer meets their needs simply because the migration process feels too complicated. Concerns usually include retraining employees, changing internal workflows, and avoiding disruptions to the customer experience.
Transition often depends on the provider’s onboarding support. Dedicated implementation teams, structured migration plans, employee training, and ongoing support can reduce much of the operational burden.
Pricing & plans
Choosing the right expense management tool often comes down to pricing. However, comparing costs can be difficult because different platforms follow different pricing models. Some charge per user, while others use usage-based pricing. In some cases, there may also be additional costs such as currency conversion fees, platform charges, or minimum monthly spending requirements.
Because of this, it is good to review the pricing structure carefully before signing a contract. The right tool should match your business needs, usage levels, and budget. Flexible pricing, convenient plans, and renewable options can support long-term growth.
Accounting & ERP integrations
Good accounting and ERP integrations help businesses export CSVs, prepare financial statements, and keep all transaction records in one place. Platforms with separate charts of accounts, approval hierarchies, and reporting views for each entity help businesses handle risk analysis and lending decisions.
As your company grows, supporting multiple accounting integrations becomes an integral part of scaling smoothly. This becomes more important for global companies, since customers in different countries use different accounting software. For example, businesses in the US may use QuickBooks, while companies in the UK often prefer Sage.
Company and budget size
Choosing a financial tool without considering your company's size and budget can create problems early on. The platform should support not only your current needs, but also your expected growth over the next 18 months. It is also important to choose a pricing model with essential features that support your company as it grows.
Building financial discipline early through automated policy enforcement, receipt capture, and GL coding helps businesses stay within budget.
Customer support & onboarding
Customer support and onboarding quality directly impact your overall business performance. Even a feature-rich tool can become difficult to use if the onboarding process is rushed, support is slow, or documentation is unclear. Teams often end up using only a small part of the platform because they were never properly guided through setup and implementation.
Dedicated onboarding managers, responsive support channels, detailed documentation, and training materials can reduce implementation issues and help teams become productive faster.
Security and compliance
Security and compliance should be treated as core requirements when choosing the right product for your company, especially for businesses handling sensitive payment or customer data. Certifications such as SOC 2 and PCI DSS help indicate whether a vendor follows established security standards.
Moreover, features like role-based access controls and fraud monitoring can reduce operational and financial risk. Businesses operating across different regions or regulated industries may also need to confirm compliance with local privacy laws and data residency requirements before moving forward.
Alternatives to Ramp and Stripe
Ramp and Stripe are both good at what they are built for, that is, to simplify day-to-day financial management, but they do not solve every business need.
Ramp is more centered around company spending and works best for US-based operations, which can be limiting for businesses handling teams or payments across different countries. Stripe is more geared toward payment processing, but growing businesses often notice how transaction fees add up, and some companies find the platform more technical than they actually need.
Businesses that want better global support or a simpler system for handling both payments and expenses usually end up looking at other options. Even after a Ramp vs. Stripe corporate card comparison, some businesses may find that neither platform fully meets their needs.
Let's dive into some alternatives to Ramp and Stripe.
Volopay
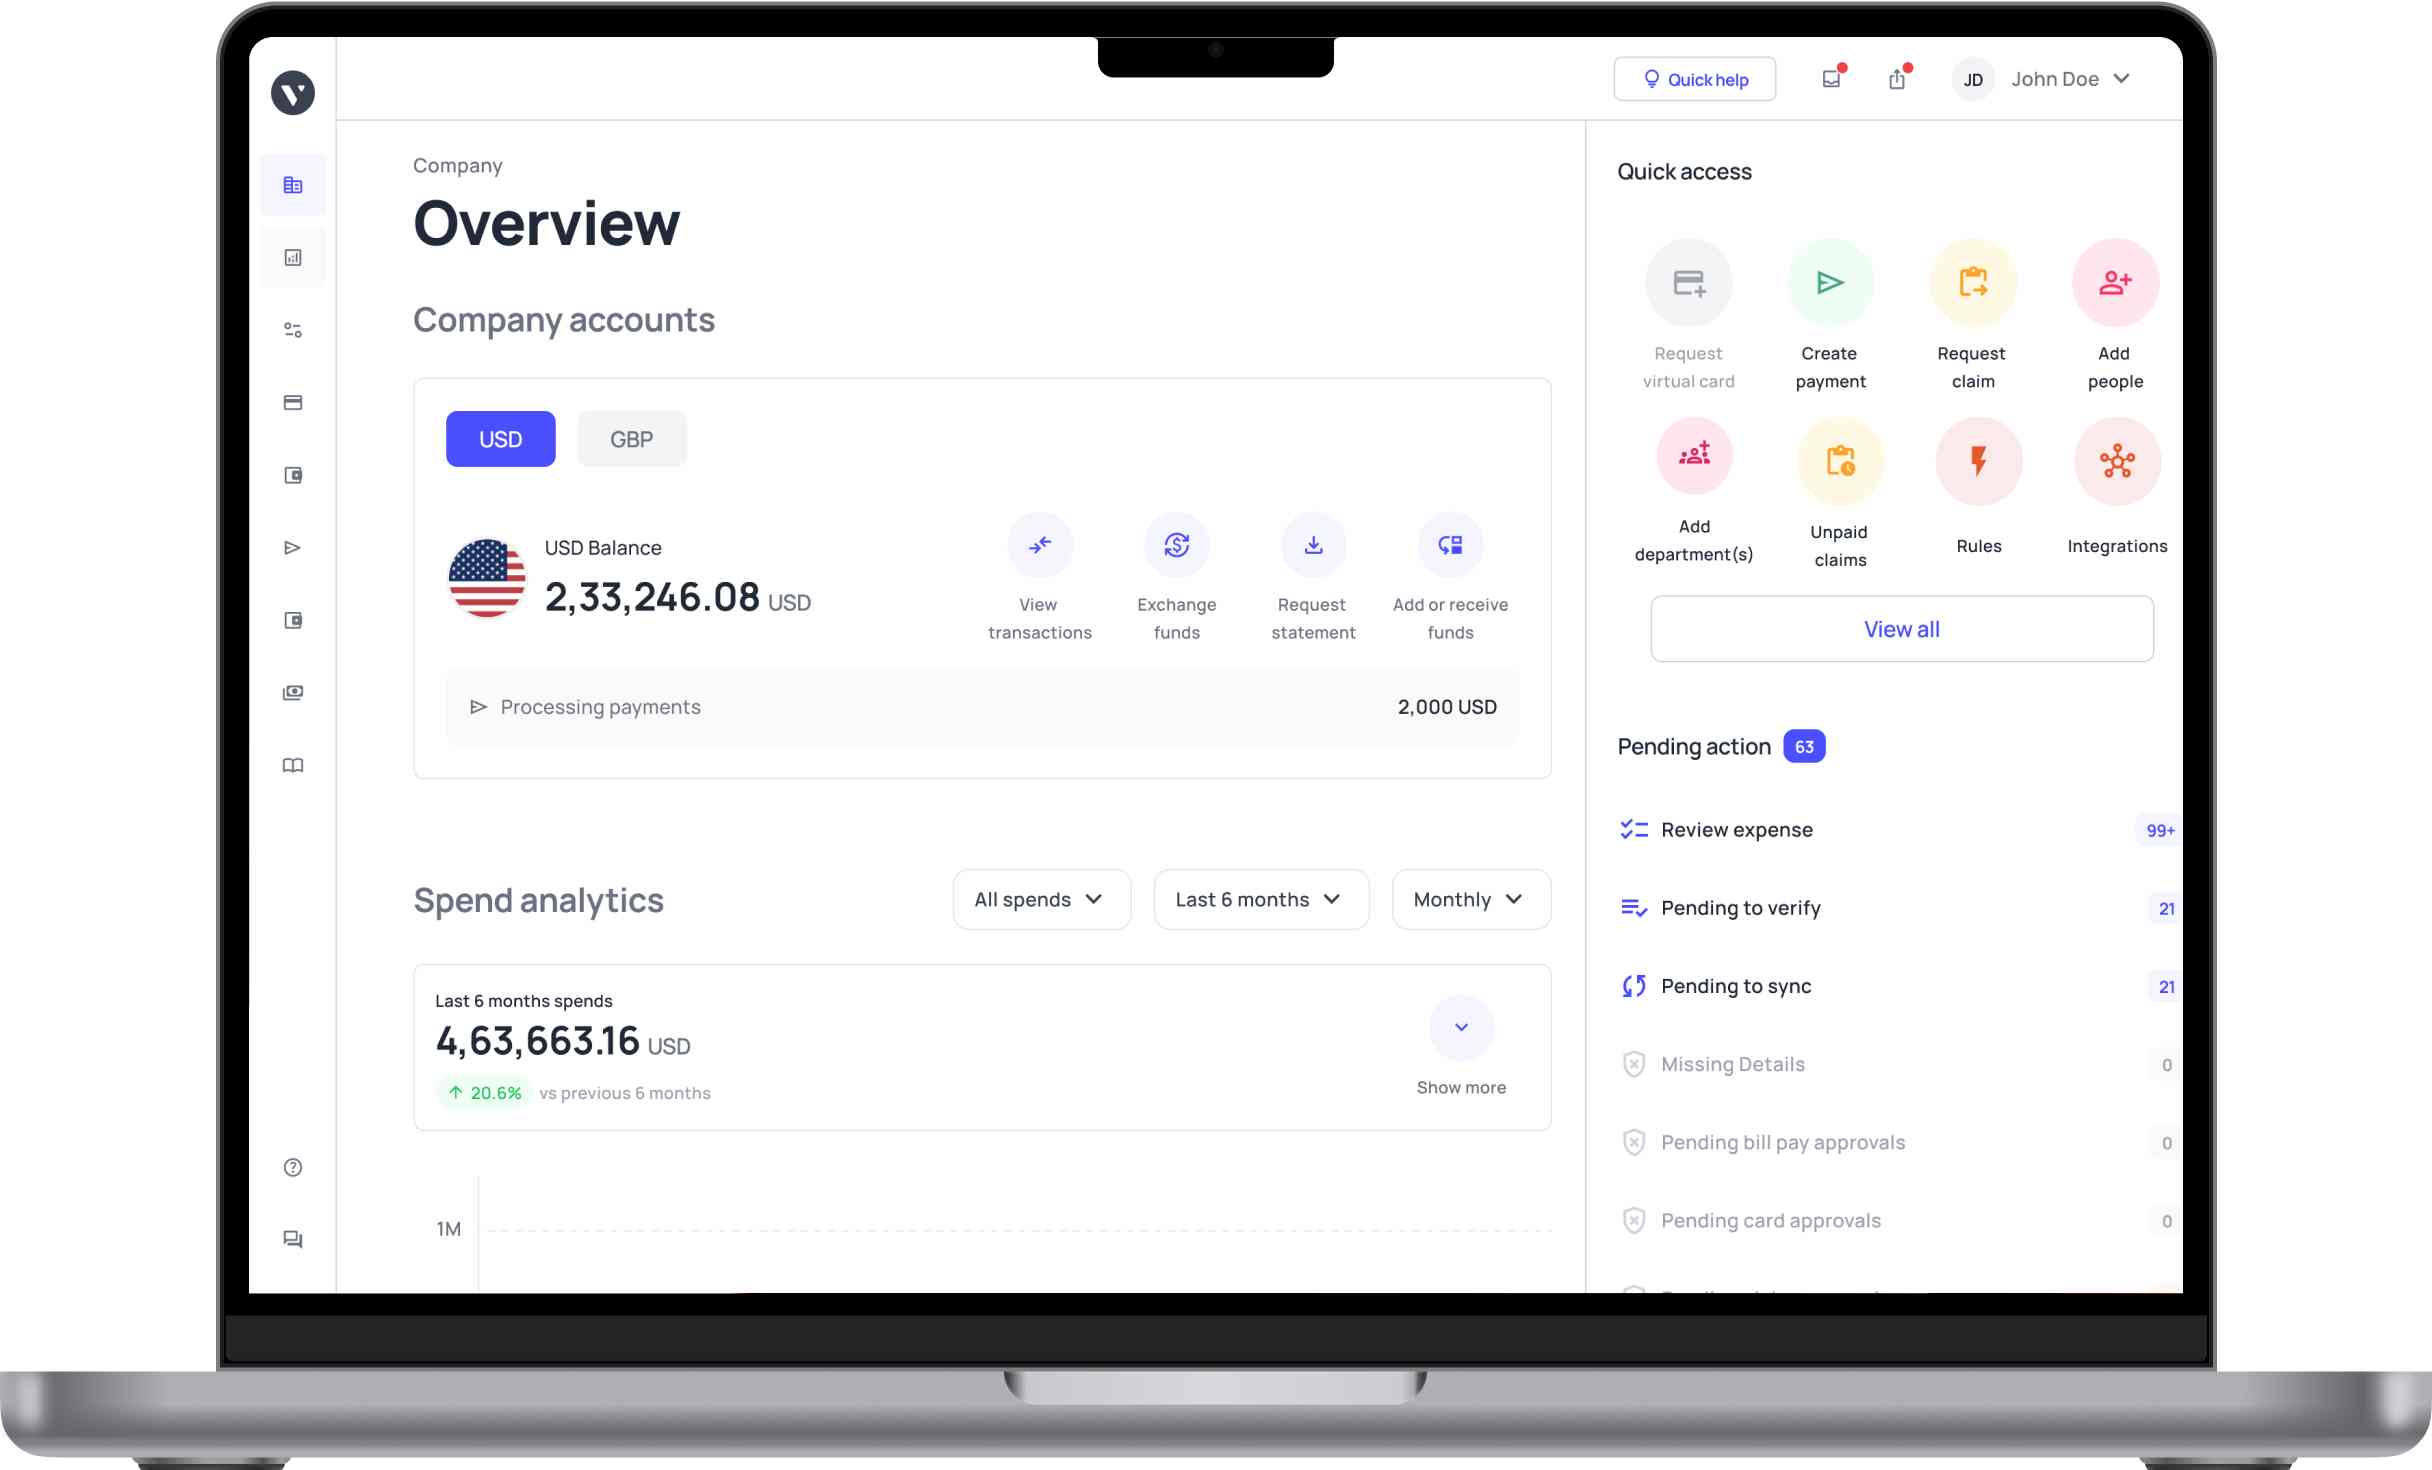
Volopay is an all-in-one business spend management and payments platform for global teams. It works well for businesses with companies, vendors, and even does operations in different countries. It is not limited to the US banking infrastructure and supports multi-currency accounts and international payments.
It also includes corporate cards, expense tracking, bill payments, and approval workflows in one platform. Its corporate cards are easy to issue, track, freeze, or replace, and every transaction is recorded in real time for better visibility. Startups also benefit from its detailed spending reports and insights, which make it easier to control budgets and manage company expenses.
Brex
Brex is a spend management platform designed for startups, scaling companies, and enterprise teams. Similar to Ramp, it offers corporate cards, expense management, bill payments, and accounting integrations in one system.
One of its advantages is international support, with local-currency corporate cards available in more than 50 countries for global teams. The downside is pricing, as Brex is generally more expensive and may not be the best fit for smaller or budget-conscious businesses.
Adyen
Adyen is an alternative to Stripe for large businesses with high payment volumes and global customers. Unlike Stripe’s flat-rate pricing model, Adyen helps enterprise companies reduce processing costs and improve payment approval rates through direct acquiring infrastructure.
However, Adyen is more suited for established businesses, as its onboarding process, pricing structure, and minimum volume requirements can be difficult for smaller companies or early-stage startups.
They loved Volopay, you will too
Financial stack for business
No more switching between multiple bank accounts and tools to run your smart business. We have combined great software with every service you are using a bank for, to produce a state-of-the-art financial platform, Volopay.
Less time spent on manual reconciliations
Faster month-end book closing turnaround
Accurate receipt matching with automation
FAQs
Ramp and Stripe are built for different purposes. Stripe helps businesses accept payments from customers, while Ramp helps companies manage spending through corporate cards, expense tracking, and bill payments.
Ramp vs. Stripe for corporate cards clearly leans more toward Ramp. Ramp offers customizable corporate cards with built-in spending controls and approval limits. On the other hand, Stripe is mainly focused on payment infrastructure and helping businesses process online payments.
Ramp does not process customer payments. Instead, it is a spend management solution with AI-powered expense controls, automatic receipt matching, real-time budget enforcement, and virtual card issuance. Meanwhile, Stripe is built for payment processing, handling large transaction volumes, bank transfers, buy now, pay later options, and more.
Ramp vs. Stripe embedded payments clearly favor Stripe. Stripe provides a complete payment ecosystem with features like Stripe Connect, Payment Links, payout splitting, and other financial services integrations.
Ramp is the better option for expense management. It covers receipt capture, non-compliant policy flagging, mileage tracking, employee reimbursements, and expense reporting.
Ramp provides a free core platform that includes unlimited virtual and physical cards, while basic bill pay comes with zero subscription cost. Ramp mainly earns through interchange fees on card transactions. Meanwhile, Stripe charges transaction-based fees, especially for international cards, currency conversion, and premium features.
Both Stripe and Ramp can be valuable for startups. Stripe is useful for accepting customer payments, whereas Ramp helps businesses manage employee spending and finance operations.
You wouldn’t usually switch from Stripe to Ramp because they solve different problems. Stripe handles incoming payments, while Ramp focuses on company spending and expense management. Regardless, if you wish to switch from Stripe to Ramp, the process is generally straightforward, but it depends on your existing integrations and workflows.
Both Ramp and Stripe function differently and are not direct competitors. Better alternatives to Ramp for spend management include Volopay and Brex, while Adyen is a common alternative to Stripe for high-volume payments.