Prepaid credit cards for Australian businesses : A practical guide to managing payments
Prepaid credit cards have quietly become one of the most powerful financial tools available to Australian businesses, yet most finance teams are still underutilising them.
This guide cuts through the noise and gives you everything you need: how prepaid cards actually work, how they compare to credit and debit alternatives, which providers are worth your attention, and how to get set up without wasting time. Whether you are managing a team of five or five hundred, what you read here will change how you think about business spending.
What is a prepaid credit card?
A prepaid credit card is a payment card loaded with a set amount of money in advance. Unlike traditional credit cards, it draws from your own deposited funds rather than a borrowed credit line, making it a practical option for budgeting and everyday spending.
Despite the name, a prepaid credit card works nothing like a traditional credit card. When you use a credit card, you're borrowing money from a lender and repaying it later. With a prepaid card, you spend only what you've already loaded onto it, so there's no debt, no interest charges, and no credit checks required.
The term "prepaid credit card" is widely used in Australia because these cards share the same card networks and can be used wherever credit cards are accepted.
Best reloadable prepaid credit cards in Australia
1. Volopay prepaid card
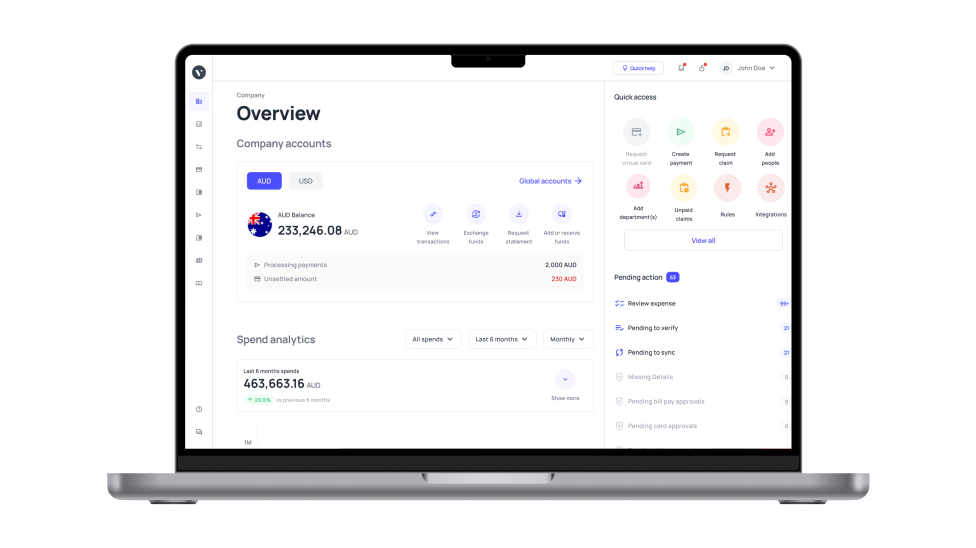
Volopay is a spend management platform built for Australian businesses that want tighter control over team expenses. The prepaid cards are virtual and physical cards that can be issued to individual team members, each with customisable spending limits and category restrictions.
You load funds onto your wallet first, and employees spend only what has been allocated, so overspending becomes structurally impossible. The card integrates directly with Xero, NetSuite, MYOB, and QuickBooks, syncing transactions in real time and reducing manual reconciliation work significantly.
Volopay also supports multi-currency wallets, making it useful for teams that deal with international suppliers or travel frequently. Approval workflows can be configured so finance teams retain visibility over every dollar before it leaves the account. Pricing is available on request and tailored to business size.
Pros:
● Real-time transaction visibility across all cards
● Direct integrations with Xero, NetSuite, MYOB, and QuickBooks
● Customisable spending limits per card or per employee
● Supports virtual and physical cards simultaneously
● Multi-currency wallet functionality
Cons:
● Better suited to teams than solo operators or freelancers
● Onboarding may take time for smaller organisations unfamiliar with spend platforms
Best for: Australian businesses wanting centralised control over employee spending with strong accounting integration.
2. Weel prepaid card
Weel (formerly DiviPay) is an Australian-built expense management tool designed to eliminate petty cash and paper receipts from business operations. Its prepaid Visa cards are issued virtually within minutes, allowing managers to assign funds to specific employees or departments without requiring a shared card arrangement.
Each card can be set with a fixed spending limit, an expiry date, or restricted to a specific merchant category, giving finance teams meaningful oversight without micromanaging every purchase.
Weel connects natively with Xero and offers CSV export compatibility for other accounting platforms. Receipt capture is built into the mobile app, so employees can photograph and attach receipts immediately after a transaction.
Weel's pricing starts at around AUD 4 per active user per month on its standard plan, with higher tiers available for larger teams needing advanced controls.
Pros:
● Instant virtual card issuance
● Built-in receipt capture via mobile app
● Merchant category restrictions are available
● Native Xero integration
● Transparent, user-based pricing model
Cons:
● Physical card options are limited compared to some competitors
● Reporting features are less advanced on entry-level plans
● International transaction fees may apply
Best for: Small to medium Australian businesses looking to digitise expense management quickly and affordably.
3. Budgetly prepaid card
Budgetly is an Australian expense management platform focused on giving finance managers real-time control over how funds are distributed and spent across their organisation.
As one of the best reloadable prepaid cards Australia has developed for local business conditions, Budgetly allows administrators to load and reload funds to individual cards instantly, set recurring budgets, and monitor balances without waiting for end-of-month statements.
Cards operate on major global networks, meaning they are accepted wherever global networks are used domestically and internationally. Budgetly integrates with Xero for automated transaction syncing, reducing the time spent on manual data entry.
The platform charges a flat monthly subscription fee rather than per-transaction pricing, which makes costs more predictable as team size grows. Pricing details are provided upon request through their website.
Pros:
● Instant reload capability from the admin dashboard
● Recurring budget scheduling for regular expenses
● Flat subscription pricing model for cost predictability
● Xero integration included
● Global network acceptance
Cons:
● Pricing is not listed publicly
● Primarily designed for businesses rather than individual consumers
● Limited information on multi-currency support
Best for: Finance teams that want predictable subscription costs and automated budget allocation across multiple cardholders.
4. Vasco prepaid card
Vasco is a travel-focused prepaid card designed for Australians who spend frequently in foreign currencies. The card allows users to load funds in AUD and convert to multiple supported currencies at competitive exchange rates, locking in rates ahead of travel or international purchases.
This makes it a practical tool for businesses with overseas suppliers, as well as individuals who travel regularly for work. Vasco does not charge monthly fees, and foreign transaction fees are competitive compared to traditional bank-issued cards.
The card is managed through a mobile app where users can track balances, view transaction history, and reload funds as needed. Accounting integration options are more limited than business-specific platforms, with CSV export being the primary method for importing transaction data into external software.
Pros:
● No monthly account fees
● Competitive foreign currency conversion rates
● Multi-currency support for international use
● Simple mobile app for balance management
● No credit check required to obtain a card
Cons:
● Limited accounting software integration
● Less suited to managing a team or multi-user spending
● Reload options may be slower than business-grade platforms
Best for: Frequent travellers and smaller businesses with regular international payment needs seeking a straightforward multi-currency prepaid option.
5. Australia Post prepaid card
The Australia Post card is one of Australia's most accessible reloadable prepaid options, available for purchase and reload at over 3,500 Australia Post outlets nationwide. It can be used for in-store, online, and phone purchases wherever global card networks are accepted in Australia and internationally.
It is a straightforward option for individuals who want to manage spending without linking a bank account. The card can be reloaded in-store at any participating post office, and balances are trackable through the Australia Post app or website. There is no bank account or credit history required to get started.
A purchase fee applies when obtaining the card (approximately AUD 5.95 to AUD 9.95 depending on the variant), and some transaction and inactivity fees may apply. Accounting integration is not a feature of this card, as it is designed for personal use rather than business expense management.
Pros:
● Available at over 3,500 Australia Post locations
● No bank account required
● Global network acceptance domestically and internationally
● Easy to reload in-store
● Simple and accessible for everyday consumers
Cons:
● No accounting software integration
● Inactivity fees may apply
● Not designed for multi-user or team expense scenarios
● Limited app functionality compared to business platforms
Best for: Individuals seeking a simple, widely accessible prepaid card for personal budgeting or one-off spending without a bank account.
| Feature | Volopay | Weel | Budgetly | Vasco | Australia post |
|---|---|---|---|---|---|
Physical card | Yes | Limited | Yes | Yes | Yes |
Virtual card | Yes | Yes | Yes | No | No |
Multi-user support | Yes | Yes | Yes | No | No |
Xero integration | Yes | Yes | Yes | No | No |
Other accounting | NetSuite, QuickBooks, MYOB | CSV export | CSV export | CSV export | None |
Multi-currency | Yes | Limited | Limited | Yes | Yes |
Monthly fee | On request | From AUD 4/user | On request | None | None |
Card purchase fee | N/A | N/A | N/A | N/A | AUD 5.95 to 9.95 |
Best for | Business teams | SMB expense management | Finance teams | Travellers | Personal use |
No credit check | Yes | Yes | Yes | Yes | Yes |
Benefits of prepaid cards for Australian businesses
Fund security
A compromised credit card can expose your entire business credit line to fraud. A hacked bank card can drain your operating account within minutes. A prepaid credit card Australia businesses use, however, limits exposure to only the funds loaded onto that card, containing any damage before it spreads to core business finances.
According to the Australian Institute of Criminology, payment card fraud costs Australian businesses hundreds of millions of dollars annually. You can view some of their findings at aic.gov.au.
Volopay strengthens the security for prepaid cards further by offering real-time transaction alerts and the ability to instantly freeze or cancel individual cards from the admin dashboard. This means suspicious activity can be stopped the moment it appears rather than discovered days later on a statement.
Spending controls
Unlike a credit card, where an employee can unknowingly overspend a policy limit, prepaid cards are hard-capped. Once the balance hits zero, the card declines. No awkward conversations, no policy violations, and no surprise bills at the end of the month.
This structure makes prepaid cards particularly effective for managing travel allowances, team lunches, software subscriptions, or any recurring expense category where budget discipline matters. Finance managers set the limit once, and the card enforces it automatically without requiring follow-up.
Volopay allows administrators to restrict spending by category as well. The policy is built into the card itself, removing the need to chase receipts or dispute claims after the fact.
No credit risk
Credit cards come with a dangerous comfort: the ability to spend money you do not have yet. For growing businesses, that flexibility can quietly become a liability as balances accumulate, interest compounds, and minimum payments start competing with operational expenses for cash flow priority.
Prepaid cards keep your business spending firmly within its actual cash flow. There are no interest charges, no minimum payments, and no revolving debt building in the background. Every dollar spent is a dollar that was already yours.
For businesses operating on tight margins or those that are scaling quickly and need to maintain financial discipline, this is a meaningful structural advantage. Volopay operates entirely on a preloaded wallet model, meaning funds must exist on the platform before any card can draw on them, giving finance leaders full confidence that spending never exceeds available cash.
Better accounting
Prepaid credit cards issued per department, project, or vendor turn expense categorisation from a monthly chore into an automatic outcome. Every transaction is tagged at the point of purchase, bucketed by the card it came from, and ready to sync into your accounting software without manual intervention.
No more month-end receipt chasing. No more guessing whether that one particular charge belonged to marketing or operations. The data is clean before it even reaches your bookkeeper.
Volopay integrates directly with Xero, QuickBooks, MYOB, and NetSuite, pushing categorised transaction data in real time. Teams can attach receipts via the mobile app immediately after spending, so by the time finance closes the month, every line item is accounted for, verified, and ready for review without a single email asking "what was this charge for?"
One-time or limited-use cards
Instead of sharing your main business account or issuing a permanent card to a new vendor, you can load a prepaid card with only the exact amount needed for that specific job. If the relationship does not work out, or the vendor charges more than agreed, your exposure stops at that pre-set balance.
Example: Suppose your business engages a freelance designer for a one-off project quoted at AUD 1,500. Rather than sharing a company card or processing a manual bank transfer, you issue a single-use virtual prepaid card loaded with AUD 1,500 and send it directly to the designer. If they attempt to charge AUD 1,800, the card declines at AUD 1,500. The project completes, the card expires, and your main accounts remain untouched throughout.
Volopay supports virtual card creation in seconds, with the ability to set expiry dates and spending ceilings, making one-time vendor payments clean, controlled, and completely isolated from your core business finances.
Simplified reconciliation
One of the best reloadable prepaid cards Australia businesses can adopt is one that does the reconciliation groundwork automatically throughout the year, not just at tax time. When cards are issued per department or cost centre, every transaction creates a categorised, timestamped record the moment it occurs.
By the time your accountant or bookkeeper sits down in the new financial year, the heavy lifting is already done. There is no manual categorisation, no missing receipts to hunt down, and no ambiguous transactions left unexplained. Just organised, accurate data ready for review.
Volopay generates exportable transaction reports by card, team, or time period, and syncs directly with leading accounting tools so that reconciliation becomes a verification task rather than a reconstruction exercise. For businesses managing GST reporting or preparing for an audit, this kind of structured data trail is essential.
Prepaid cards vs. credit cards vs. debit cards
Choosing the right payment card for your business comes down to how you want to manage funds and risks. Each card type serves a different financial purpose, and understanding those differences helps Australian businesses make smarter spending decisions.
A prepaid credit card Australia businesses rely on requires no bank account and carries no debt risk, since you spend only what has been loaded. A traditional credit card, on the other hand, offers a borrowing facility up to an approved limit, with interest applied to unpaid balances.
A debit card draws directly from a linked bank account, meaning every transaction reduces your live operating balance immediately. For businesses prioritising budget control, fraud containment, and clean reconciliation, prepaid cards offer structural advantages that neither credit nor debit cards can replicate natively.
| Feature | Prepaid card | Credit card | Debit card |
|---|---|---|---|
Linked to a bank account | No | No | Yes |
Spends borrowed funds | No | Yes | No |
Interest charges | None | Yes, if unpaid | None |
Credit check required | No | Yes | Sometimes |
Spending limit | Preloaded amount | Approved credit limit | Available account balance |
Fraud exposure | Limited to loaded funds | Up to full credit limit | Entire account balance |
Reloadable | Yes | Not applicable | Not applicable |
Suitable for employee use | Yes | Risky | Risky |
Accounting integration | Available on business platforms | Limited | Limited |
Available in Australia | Yes | Yes | Yes |
How to get a prepaid card in Australia
Getting a prepaid card in Australia is a straightforward process, though the steps vary depending on whether you are an individual consumer or a business seeking a managed spend solution. For most business platforms, the entire process can be completed within a few business days.
General steps to obtain a prepaid card
● Choose a provider that suits your business needs, whether that is a consumer-facing option or a business spend platform.
● Submit an application through the provider's website or in store. Business platforms typically require an ABN, proof of identity, and basic company details.
● Complete identity verification in line with Australian Anti-Money Laundering and Know Your Customer (KYC) requirements. This usually involves uploading a driver's licence or passport.
● Fund your account by transferring an initial AUD amount into the platform wallet or onto the card directly.
● Issue cards to yourself or team members, set spending limits, and configure any category restrictions before activating.
Most consumer prepaid cards are available same-day and in store. Business platforms typically take between two and five business days from application to card activation, depending on verification requirements.
Volopay onboarding process for Australian businesses
Volopay is one of the best reloadable prepaid cards Australia has available for businesses wanting a fully managed spend platform. The onboarding process is handled by a dedicated team member who guides you through every step rather than leaving you to navigate a generic sign-up flow alone.
● Step 1: Contact us through the website to connect with a product specialist who will assess your business requirements.
● Step 2: Submit your business documentation, including ABN, director identification, and company registration details for compliance verification.
● Step 3: Complete the KYC and onboarding review, which our team processes on your behalf with guided support throughout.
● Step 4: Fund your Volopay wallet with an initial AUD deposit once your account is approved and configured.
● Step 5: Begin issuing virtual or physical prepaid credit cards to team members immediately, with spending controls and accounting integrations activated from day one.
The full Volopay onboarding process typically takes a few days, depending on documentation readiness and verification outcomes. Businesses that prepare their compliance documents in advance tend to move through onboarding at the faster end of that window.
How do prepaid credit cards work?
Mechanism of loading funds
Users can load funds onto prepaid credit cards through various methods like direct deposit, bank transfers, or cash deposits at designated locations.
This process allows individuals to control the amount they spend, as the card balance cannot exceed the limit of the loaded amount.
Transaction process and limitations
Transactions with reloadable prepaid credit cards involve the same process as regular credit cards—swiping, tapping, or entering card details online.
However, these cards come with limitations. Once the prepaid amount is exhausted, further transactions are declined unless more funds are added.
Distinctions from traditional cards
Prepaid cards don't involve credit extensions, so there's no risk of accruing interest or affecting credit scores.
They also don't require credit checks during issuance, making them accessible to individuals with varied financial backgrounds. Additionally, they offer a level of privacy, as they aren't linked to personal bank accounts.
How do prepaid credit cards differ from prepaid debit cards?
When choosing between prepaid credit cards and prepaid debit cards in Australia, you need to understand their key differences to make an informed decision. Here’s a breakdown of how they compare across several factors.
1. Source of funds
What is a prepaid credit card? A prepaid credit card requires you to load money onto the card beforehand, creating a spending balance that functions like available credit. Unlike traditional credit cards, prepaid credit cards in Australia aren't connected to bank accounts or credit facilities.
Reloadable prepaid credit cards allow you to add funds multiple times. Prepaid debit cards operate differently, drawing funds directly from your linked bank account with each transaction, similar to standard debit cards.
2. Spending limit
Your prepaid credit card spending capacity equals exactly what you've loaded onto it, preventing overspending entirely. This makes reloadable prepaid credit cards excellent budgeting tools.
Prepaid debit cards limit spending based on your bank account balance, which might permit overdrafts if your bank allows them, potentially resulting in costly overdraft fees that prepaid credit cards in Australia help you avoid completely.
3. Fees and costs involved
Prepaid credit cards typically charge activation fees, reload fees, or monthly maintenance costs, but eliminate interest charges since no borrowing occurs. What is a prepaid credit card's advantage here? No debt accumulation.
Prepaid debit cards generally have lower fees since they connect to existing bank accounts, though you might encounter overdraft or transaction fees based on your bank's specific policies and account terms.
4. Approval process
Obtaining a prepaid credit card requires no credit check, making these cards accessible for individuals with poor credit or no credit history. Reloadable prepaid credit cards follow the same no-credit-check policy.
Prepaid debit cards also skip credit checks but require an active bank account for linkage. Both prepaid credit cards in Australia and prepaid debit cards may require basic identity verification during application.
5. Impact on credit
Using a prepaid credit card doesn't influence your credit score since you're spending preloaded funds rather than borrowing money. What is a prepaid credit card's credit impact? None whatsoever.
Similarly, prepaid debit cards don't affect credit scores because they access your existing bank funds without involving credit facilities or reporting transaction history to credit bureaus, maintaining credit neutrality.
6. Rewards and perks
Prepaid credit cards rarely provide rewards programs or perks, as they focus on spending control rather than purchase incentives. Reloadable prepaid credit cards prioritize financial management over rewards.
Prepaid debit cards might offer limited rewards through associated bank programs, but these benefits are uncommon and typically less attractive than traditional credit card reward schemes available in the market.
7. Use cases
Prepaid credit cards excel for online shopping, international travel, or gift-giving, providing transaction flexibility without debt risks. What is a prepaid credit card best used for? Controlled spending scenarios.
Prepaid debit cards work well for routine transactions like grocery shopping or bill payments, accessing your bank account directly, though they lack the precise budgeting control that prepaid credit cards in Australia offer users.
What are the perks of using prepaid credit cards?
Reduced risk of exceeding budget
Prepaid cards let users spend only the amount loaded in them. This removes the chance of overspending and aids in disciplined budget management.
This feature is particularly beneficial for businesses that want to let their employees make expenses freely but are also aiming to control their expenses effectively.
More secure than cash
Prepaid cards offer enhanced security compared to carrying cash. If lost or stolen, these cards can be reported and deactivated easily through a mobile app, preventing unauthorized use.
Additionally, many providers offer fraud protection, shielding users from liability for unauthorized transactions.
Convenient reload and usage
Users can conveniently reload prepaid cards through multiple channels, including online transfers, mobile apps, and retail locations. Their widespread acceptance of transactions, both online and offline, makes them a convenient payment method for employees.
Banking alternative
For individuals without traditional bank accounts or those looking to separate spending funds from their primary bank account, prepaid cards serve as an alternative. They offer similar functionalities without the need for a traditional banking relationship.
Safe payment alternative
Prepaid cards offer a safer alternative to carrying cash, especially during travel. They mitigate the risk of loss or theft while providing the flexibility of electronic payments worldwide.
Financial control and budgeting
One of the most significant advantages of prepaid cards is the control they provide over finances.
Users can allocate specific amounts for various expenses, aiding in better budgeting and financial planning. This feature is instrumental for those aiming to improve their spending habits or manage irregular income.
What are the limitations of prepaid credit cards?
Fees/charges
Prepaid cards often come with various fees, including activation fees, monthly maintenance fees, ATM withdrawal fees, and reloading charges. Users should scrutinize the fee structure to understand the costs associated with using the card.
No elevation in credit scores
Unlike traditional credit cards, prepaid cards do not contribute to building credit history or improving credit scores. They operate independently of credit bureaus, so responsible usage doesn't impact credit ratings positively.
Load limits
Prepaid cards may have limitations on the maximum amount users can load onto the card. These load limits vary among providers and can affect the card's utility for significant expenses or transactions.
Withdrawal limitations
ATM withdrawal limitations are common with prepaid cards. Users might encounter restrictions on the amount they can withdraw daily or per transaction, potentially affecting access to funds in emergencies.
Reload options
While reload options for prepaid cards are versatile, certain methods might incur additional fees or have processing delays. Users should consider the convenience and cost implications when choosing reloading methods.
Use cases for prepaid credit cards in business
Employee expense management
You can issue prepaid credit cards to employees for work-related expenses like travel or client meetings. What is a prepaid credit card here—a tool for complete budget control.
Preloaded amounts ensure spending stays within budget limits, simplifying expense tracking and reducing reimbursement hassles for your business operations effectively and efficiently.
Department or project budget control
Assign reloadable prepaid credit cards to specific departments or projects with fixed budgets allocated precisely.
You control the funds loaded onto each card, ensuring teams stick to allocated amounts without overspending, while maintaining clear financial oversight and accountability across all business units.
Payments to freelancers or contractors
Pay freelancers or contractors with prepaid credit cards in Australia to streamline payment transactions efficiently.
You preload exact amounts for services rendered, avoiding delays with traditional bank transfers and ensuring secure, traceable payments that benefit both parties in business relationships and partnerships.
Staff incentives, bonuses, or rewards
Use prepaid credit cards as incentives or bonuses for your staff members effectively.
Load specific amounts as rewards for outstanding performance, offering a tangible, flexible benefit that employees can use for personal purchases, boosting morale and motivation across your workforce, and improving employee satisfaction.
Online subscriptions and digital ads
Manage recurring expenses like software subscriptions or digital advertising campaigns with reloadable prepaid credit cards strategically.
You can allocate precise budgets for these ongoing costs, preventing unexpected charges and simplifying expense categorization for better financial management and control while reducing administrative overhead.
Fraud risk limitation for specific vendors
Limit fraud exposure by using prepaid credit cards for payments to new or unverified vendors safely. Limited exposure is a major advantage of prepaid credit cards.
You load only the required payment amount, reducing the risk of unauthorized charges compared to linked bank accounts and protecting business finances.
Travel and event-related spending
Provide prepaid credit cards in Australia for business travel or event expenses management.
You set specific spending limits for flights, accommodation, or catering costs, ensuring employees stay within budget while simplifying expense reporting and maintaining financial control over business activities and travel expenses.
Temporary staff or seasonal purchase needs
For temporary staff or seasonal purchases, reloadable prepaid credit cards offer a controlled way to manage specific expenses effectively.
You load funds for particular needs, like holiday inventory purchases, without exposing primary business accounts to unnecessary financial risks or complications while maintaining security.
Factors to consider when choosing your prepaid credit card
Fee structure
Thoroughly review the fee structure associated with the prepaid card. Look out for activation fees, monthly maintenance charges, ATM withdrawal fees, inactivity fees, and other additional charges.
Some cards may offer fee waivers based on regular usage or direct deposit criteria. Understanding and comparing these will help you select a card that aligns with your financial habits and minimize unnecessary costs.
Security measures
Prioritize prepaid cards with robust security features to safeguard your finances. Look for cards equipped with EMV chip technology, two-factor authentication, fraud protection, and zero liability policies.
These security measures ensure enhanced protection against unauthorized transactions and fraudulent activities, offering peace of mind while using the card for transactions online or in person.
Reviews and ratings
Prioritize cards with positive user reviews and high ratings. These insights provide valuable information about the card issuer's customer service, ease of use, reliability, and any potential issues that other users might have encountered.
Online forums, review websites, and official issuer websites are great resources to gather this information.
Reload options
Evaluate the available reload options offered by the card issuer. These can include direct deposit, bank transfers, mobile apps, cash reloads at retail locations, and online transfers.
Consider the convenience, frequency, and associated fees of these options to select the most suitable method for all of your reloading needs.
Network acceptance
Ensure the prepaid card is accepted widely across various networks and merchants, both domestically and internationally.
Check for logos such as Visa, Mastercard, or other major payment networks to ensure broad acceptance, enabling you to use the card conveniently wherever you go.
Card type and usage
Consider the purpose for which you intend to use the prepaid card. Some cards are tailored for general spending, while others offer travel perks, rewards, or specific benefits for online purchases.
Assess the card's features, rewards programs, and benefits to match them with your spending habits and lifestyle needs.
Qualification criteria for obtaining a prepaid credit card
The qualification criteria for obtaining a business prepaid credit card can vary depending on the card issuer and the specific type of prepaid card. However, here are some common criteria that businesses may need to meet:
Business entity (need to have a registered entity)
To acquire a prepaid credit card for business purposes, it's generally required to have a registered business entity. This could be a sole proprietorship, partnership, limited liability company (LLC), or corporation, depending on the issuer's specific criteria.
The registration ensures the legal standing and legitimacy of the business entity applying for the card.
Business documentation
Applicants typically need to provide specific business documentation during the application process.
This might include copies of business registration certificates, tax identification numbers (TINs), articles of incorporation, or any other relevant legal documents that validate the existence and structure of the business.
Credit check
One of the advantages of prepaid credit cards is that they usually do not involve credit checks during the application process.
This accessibility makes them available to individuals and businesses, regardless of their credit history, making it an attractive option for those with limited or poor credit scores.
Business information
Applicants are generally required to furnish fundamental business information.
This includes details such as the legal business name, physical business address, contact information, and sometimes a brief overview or description of the nature of the business or its operations.
Employee information (if applicable)
For business cards intended for multiple employee use, issuers may ask for details about authorized card users.
This could include their names, positions within the company, and contact information. This information helps link the card to the business entity and manage usage across multiple employees.
Annual revenue details (if applicable - all providers may not ask for this)
Certain prepaid card issuers might request annual revenue details to assess the financial standing of the business. This information can assist in determining suitable spending limits aligned with the company's income.
However, not all providers may require this information, as the qualification criteria can vary significantly among different issuers.
Best practices for effective use of prepaid credit card
Set a budget
Establish a clear budget and allocate funds to the prepaid card accordingly. This helps in controlling expenses and prevents overspending by ensuring that expenditures align with financial goals.
Segregate expenses
Maintain a clear demarcation between business and personal expenses by using separate prepaid cards for each. This segregation simplifies accounting, bookkeeping, and tax filing processes.
Check acceptance
Before using the card, verify its acceptance at the intended locations, especially if planning to use it for international money transfers. Ensuring this will prevent inconvenience during transactions.
Load wisely
Strategically load funds onto the card based on planned expenses and financial capabilities. Avoid overloading the card with unnecessary funds to minimize the risk of loss or theft.
Monitor transactions
Regularly monitor card transactions through online portals or mobile apps provided by the issuer. This practice enables timely identification of any unauthorized or suspicious activities and facilitates accurate budget tracking.
Review T&Cs
Thoroughly review the terms and conditions provided by the issuer. Understand the fee structure, transaction limits, reload options, and other pertinent information to maximize the card's benefits and minimize avoidable costs.
Legal and compliance considerations for prepaid credit cards in Australia
1. Use AFSL-licensed card issuers
Choose prepaid credit card issuers with an Australian Financial Services Licence (AFSL) for maximum protection. AFSL compliance is non-negotiable when choosing a card that works for your business.
This ensures they meet strict regulatory standards set by ASIC, providing you with reliable and compliant financial products for your business operations across Australia.
2. Comply with AML/CTF regulations
You must adhere to Anti-Money Laundering and Counter-Terrorism Financing (AML/CTF) regulations when using prepaid credit cards in Australia.
This includes reporting suspicious transactions and ensuring your reloadable prepaid credit cards usage aligns with AUSTRAC's compliance requirements to maintain legal business operations and avoid penalties.
3. Verify user identity (KYC)
Know Your Customer (KYC) rules require you to verify the identity of all cardholders using prepaid credit cards.
Ensure employees or recipients provide valid identification documents to comply with Australian regulations and prevent fraudulent use. Properly done KYC ensures that compliance is in check.
4. Review Product Disclosure Statement
Before using any prepaid credit cards in Australia, carefully review the issuer's Product Disclosure Statement (PDS).
It outlines comprehensive fees, terms, and conditions, helping you understand the card's limitations and avoid unexpected costs that could impact your business budget and financial planning strategies.
5. Follow Privacy Act requirements
Under Australia's Privacy Act, you must protect cardholder data, including personal and financial information, when using reloadable prepaid credit cards.
Ensure secure handling and storage of sensitive data to comply with privacy regulations and avoid costly breaches that could damage your business reputation and incur legal penalties.
Security tips for using prepaid credit cards for your business
1. Register all cards immediately
Register each prepaid credit card with the issuer immediately upon receipt for optimal security. What is a prepaid credit card activation’s first step? Immediate registration.
This enables comprehensive tracking, fraud protection, and the ability to freeze or replace lost or stolen cards quickly, protecting your business assets effectively.
2. Assign cards to individual employees
Issue prepaid credit cards in Australia to specific employees rather than sharing them among multiple users.
This ensures clear accountability, simplifies tracking of business expenses, and reduces the risk of misuse or unauthorized transactions within your organization while maintaining proper financial controls and oversight.
3. Restrict merchant or category usage
Set specific restrictions on where and how reloadable prepaid credit cards can be used, such as limiting them to particular merchants or categories like travel or office supplies.
This prevents misuse and ensures spending aligns with approved business needs while maintaining budget control and expense management.
4. Use secure, verified reload methods
Reload prepaid credit cards using only secure methods, like verified bank transfers or trusted payment platforms approved by your organization.
Avoid unverified third-party services to minimize the risk of fraud or unauthorized access to business funds, maintain financial security, and protect your company's assets.
5. Store physical cards securely
Keep physical prepaid credit cards in Australia in secure locations, such as locked safes or secure storage facilities, when not actively in use.
This prevents theft or unauthorized access, protecting your business's financial assets and ensuring that only authorized personnel can access these important financial tools.
6. Train staff on proper usage
Educate employees comprehensively on correct prepaid credit card usage, including spending limits, approved merchants, and procedures for reporting lost cards.
Proper staff training is a requirement. This ensures compliance with your policies and reduces the risk of costly errors or fraudulent activities.
What makes Volopay the go-to choice for business prepaid cards?
1. User-friendly
Volopay offers a user-friendly interface and intuitive features, making it easy for businesses to navigate and manage their prepaid cards efficiently. Employees can also easily access the platform through our mobile app removing the need to constantly open your laptop for expense management tasks.
2. Adherence & safety
The platform prioritizes strict adherence to industry standards for security measures, ensuring the safety of transactions and sensitive financial information.
3. Transparent pricing, no concealed charges
Volopay maintains transparent pricing structures without hidden fees, allowing businesses to have a clear understanding of costs associated with card usage.
4. Use your funds anywhere
The flexibility of Volopay's prepaid cards enables businesses to utilize funds globally, facilitating transactions across various locations and currencies.
5. Automated payments for improved cash flow
Volopay offers automated payment capabilities, streamlining financial processes and enhancing cash flow management for businesses.
6. Effortless expense and transaction management
The platform provides tools for effortless transaction tracking and expense management, simplifying financial record-keeping and auditing processes. Transactions are recorded in real-time in a central ledger on Volopay’s platform.
7. Segregate expenses
Volopay enables businesses to segregate expenses by assigning different cards or categories, facilitating accurate accounting automation and expense allocation.
FAQs
Prepaid credit cards don't require a specific credit score for approval. They are accessible to individuals regardless of their credit history, making them suitable for businesses with low or no credit scores.
Factors to consider include fee structures, card usage flexibility, network acceptance, security features, reload options, and additional benefits such as rewards or travel perks that align with your spending habits or the needs of your organization.
Different providers will have slightly differing periods within which they can deliver your prepaid credit cards. Some issuers may offer instant issuance in-person or virtually, while others might take a few days to process and deliver the card to your registered address.
Volopay's prepaid cards stand out due to their user-friendly interface, stringent security measures, transparent pricing devoid of hidden charges, automated payment capabilities, and effortless expense management through our web and mobile app.
Funds can be loaded onto a prepaid credit card through various methods, including direct deposit, bank transfers, cash reloads at designated locations, mobile apps, or online transfers from linked accounts.
Volopay employs robust security measures such as EMV chip technology, two-factor authentication, encryption protocols, and fraud monitoring to safeguard transactions from unauthorized access or fraudulent activities.
Yes, Volopay prepaid cards offer secure online transaction capabilities. The cards are equipped with advanced security features to protect against fraudulent online activities, ensuring safe and secure transactions for users. We also offer virtual prepaid cards that are tokenized in nature making them even more secure for online payments as compared to physical cards.